Capacity as an edge
Large asset managers have to favor strategies that can absorb billions. We pursue opportunities whose limited capacity makes them impractical at that scale, and keep each strategy within what it can absorb.
Machine learning, guided by financial economics. Designed to go beyond traditional factor models.
In finance, µ (mu) represents expected return: a central concept in every investment decision. At the same time, mucm is formed from the initials of our two founders.
It defines what we do: our models learn, in a purely systematic way, which characteristics distinguish stocks that tend to outperform.
Large asset managers have to favor strategies that can absorb billions. We pursue opportunities whose limited capacity makes them impractical at that scale, and keep each strategy within what it can absorb.
Our models learn from data but stay anchored in economic reasoning. They look beyond classic factor models, while long-term rewarded factor premia give portfolios a diversified, risk-conscious foundation. As markets, data and methods evolve, so do our models.
We invest with a long-term mindset, looking beyond short-term market movements and remaining patient when opportunities take time to unfold. We avoid concentrated bets and size every position with liquidity in mind, making full use of the breadth systematic investing offers.
Beta is available at scale. Alpha is not.
Our core equity strategies cover all equity markets, in long-only and long-short versions. Most are implemented as mandates; two are also available as actively managed certificates (AMCs) for qualified investors in Switzerland, with daily liquidity.
Every investor has different needs. Our modular investment platform lets us tailor equity portfolios to each client’s specific requirements, such as investment universe, risk budget, exclusions or factor preferences. This approach draws on the founders’ long experience building portfolios for institutional investors.
Marcial Messmer and Ulrich Carl met at the University of St.Gallen, where they completed their Master’s and PhD programmes together. Both later served as lead quantitative researchers in UBS Asset Management’s multi-billion quantitative equity business.
They share the same investment beliefs and work by one motto: better never stops.
The founders invest their own capital alongside our clients, so our interests are fully aligned. mu Capital Management is independent, partner-owned and has a live track record since 2023.
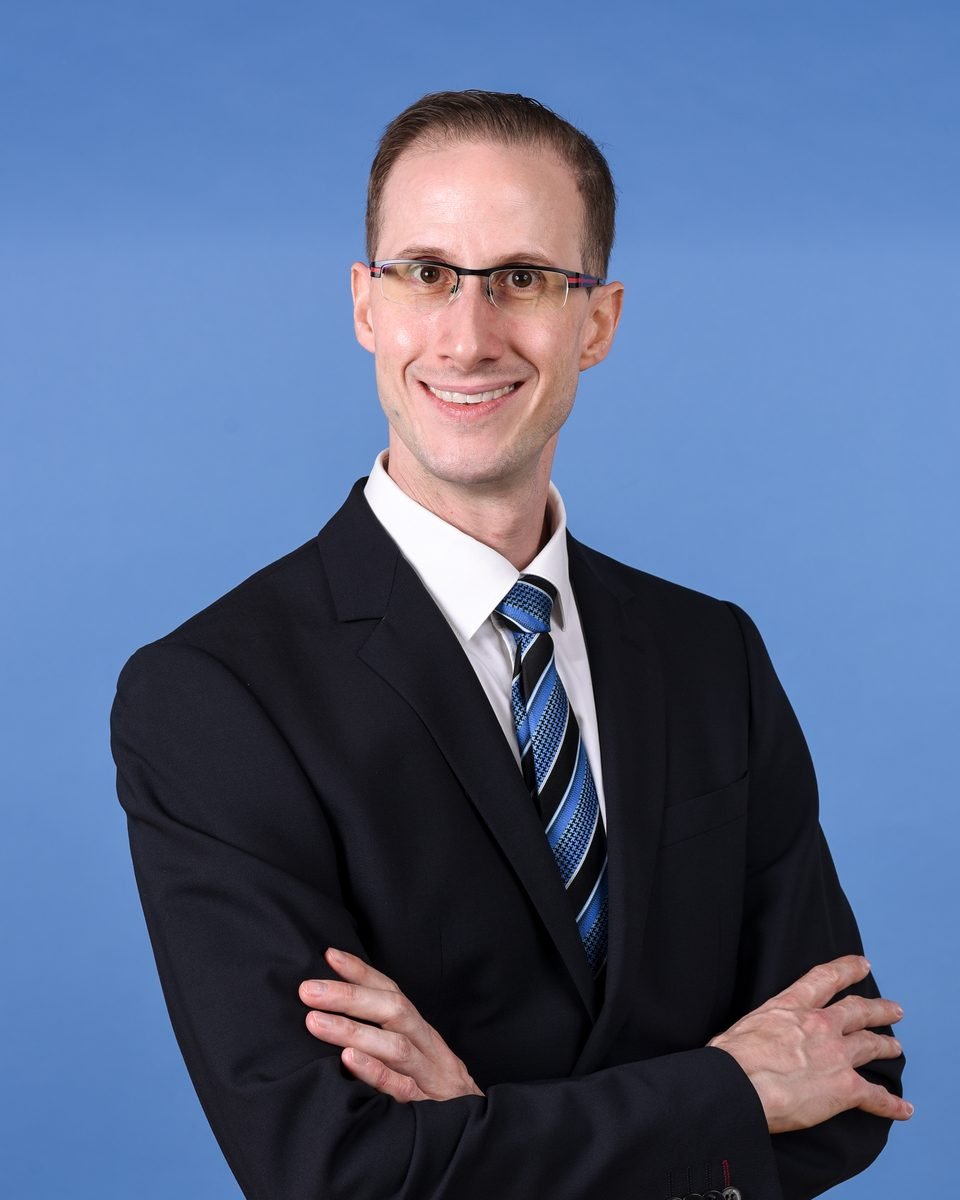
Founding Partner
Ulrich Carl is a founding partner of mu Capital Management. He was previously a quantitative researcher at UBS Asset Management and head of research at a Swiss systematic investment boutique, where he also worked as a portfolio manager alongside his doctoral studies. He holds a PhD in Economics and Finance from the University of St.Gallen (HSG), with research on factor investing, portfolio rebalancing and reconstitution effects. He received the award for the best Master’s degree in Quantitative Economics and Finance and is a CAIA charterholder.
LinkedIn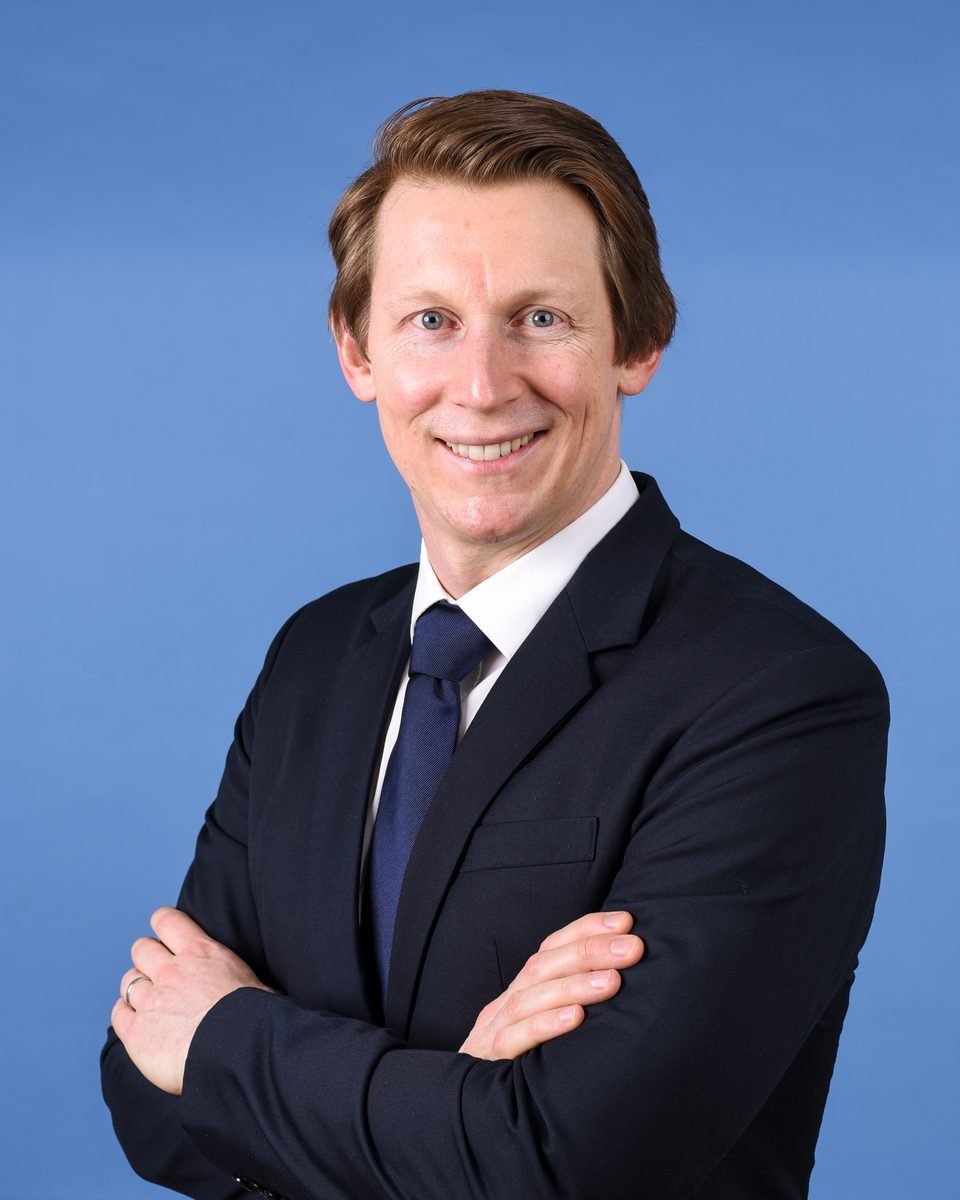
Founding Partner
Marcial Messmer is a founding partner of mu Capital Management. He was previously a quantitative researcher at UBS Asset Management and, before that, managed a global quantitative equity fund at a Zurich-based boutique. He holds a PhD in Economics and Finance from the University of St.Gallen (HSG), where his dissertation was among the early academic work applying machine learning to the cross-section of expected stock returns. He was also a visiting researcher at Columbia University.
LinkedInRequest a meeting, or ask for our materials.